Starting a mutual fund SIP is relatively easy. The bigger challenge is ensuring that the amount you invest today remains meaningful 10, 15 or 20 years later. An SIP of ₹5,000 per month may fit your budget when you are 25, but if your salary rises substantially over the next decade while your SIP remains unchanged, your investment rate effectively falls relative to your income.
A Step-Up SIP, also known as a Top-Up SIP, addresses this problem by allowing investors to increase their SIP contribution periodically. Instead of investing the same ₹5,000 every month for 20 years, you might increase it by 10% every year. As income grows, more money gets invested, giving a larger amount the opportunity to compound over the remaining investment period.
For Indian investors saving for retirement, children’s education, a house or long-term wealth creation, this simple strategy can make a major difference. It combines three powerful elements—regular investing, increasing contributions and long-term compounding. However, higher contributions do not guarantee higher market returns, and a Step-Up SIP must still be linked to realistic financial goals and an appropriate mutual fund.
What Is a Step-Up SIP?
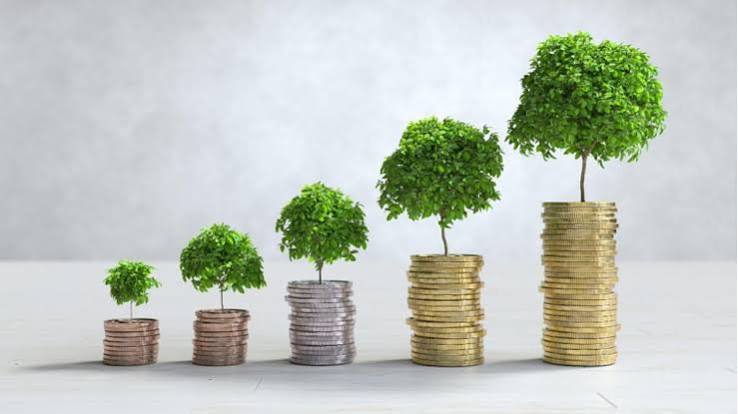
A Step-Up SIP is a Systematic Investment Plan in which the investment amount increases at predetermined intervals.
Suppose you start an SIP of ₹10,000 per month and choose an annual 10% step-up.
Your monthly investment would approximately become:
- Year 1: ₹10,000
- Year 2: ₹11,000
- Year 3: ₹12,100
- Year 4: ₹13,310
- Year 5: ₹14,641
The contribution continues increasing according to the selected step-up instruction.
Depending on the mutual fund or investment platform, the increase may be structured as:
Percentage-based: Increase the SIP by a specified percentage, such as 10% every year.
Fixed-amount: Increase it by a fixed amount, such as ₹1,000 or ₹2,000 annually.
The exact facility and rules can differ between fund houses and platforms.
Why Keeping the Same SIP for 20 Years May Not Be Enough
A fixed SIP is useful, but your financial life does not remain fixed.
Over time:
- Salary may increase.
- Household expenses rise.
- Financial responsibilities change.
- Inflation increases the future cost of goals.
- Your ability to save may improve.
Suppose you earn ₹50,000 per month and invest ₹5,000. You are investing 10% of your monthly income.
Ten years later, your income could be considerably higher. If the SIP remains ₹5,000, the contribution may represent a much smaller percentage of your salary.
A Step-Up SIP allows investments to grow alongside earning capacity rather than remaining frozen at the amount you could afford years earlier.
How Step-Up SIP Can Accelerate Wealth Creation
The biggest advantage is straightforward: you invest progressively more money.
Compounding then has a larger capital base to work on.
Consider a simplified illustration.
Assume an investor starts with a monthly SIP of ₹10,000 and invests for 20 years.
If the SIP remains fixed, the total contribution is:
₹10,000 × 12 × 20 = ₹24 lakh
Now imagine the investor increases the monthly SIP by 10% every year.
Over the same 20-year period, the total amount contributed becomes dramatically larger because every year’s contribution is higher than the previous year’s.
If both portfolios earn the same return, the Step-Up SIP can accumulate substantially more simply because much more capital has been invested.
The difference is not financial magic. It comes from higher contributions plus compounding.
The Power of Compounding With Increasing Contributions
Compounding means that investment returns can themselves participate in future returns.
Suppose an investment earns a return in one year. In subsequent years, both the original capital and accumulated gains remain invested, subject to market movements.
With a Step-Up SIP, another element is added: fresh contributions are also increasing.
This creates three drivers of potential wealth accumulation:
- Existing investments remain invested.
- Potential returns can compound over time.
- New contributions increase periodically.
The earlier the SIP is increased, the more time those additional contributions have to potentially grow.
That is why even a modest annual step-up can have a meaningful effect over a 15- or 20-year investment horizon.
Step-Up SIP Helps Fight Inflation
Long-term financial goals become more expensive because of inflation.
Suppose higher education costs ₹20 lakh today. If education expenses continue rising over the next 15 years, the amount required when your child actually enters college could be significantly higher.
The same issue affects:
- Retirement expenses
- Property costs
- Healthcare
- Weddings
- Travel
- Lifestyle expenses
If your target keeps increasing but your monthly investment remains unchanged, you may gradually fall behind.
Increasing the SIP periodically helps your investment contribution keep pace with rising future requirements.
It does not eliminate inflation risk, but it can make your savings plan more responsive to it.
Step-Up SIP Can Match Annual Salary Increments
For salaried Indian investors, one of the easiest strategies is to link the SIP increase to annual salary growth.
Suppose your salary increases by 10% and you increase your SIP by the same percentage.
Instead of allowing the entire increment to become additional lifestyle spending, part of it automatically goes toward future goals.
For example:
Current salary: ₹70,000 per month
Current SIP: ₹10,000 per month
After an increment:
New salary: ₹77,000 per month
New SIP after 10% step-up: ₹11,000 per month
Your salary has increased by ₹7,000, but the SIP rises by only ₹1,000.
This makes the additional investment relatively manageable while improving long-term savings.
Step-Up SIP Can Reduce Lifestyle Inflation
As income increases, spending often rises automatically.
A person who receives a salary increase may upgrade:
- Smartphone
- Car
- Holidays
- Dining habits
- Clothing
- Subscriptions
- Housing
Improving your lifestyle is not inherently wrong. The problem occurs when spending absorbs every salary increment while investments remain unchanged.
An automatic Step-Up SIP creates a simple rule:
Income rises → investment also rises.
This can help ensure that financial progress accompanies lifestyle improvements.
Fixed SIP vs Step-Up SIP
Both strategies create investment discipline, but their long-term behaviour differs.
Fixed SIP
The same amount is invested throughout the period.
For example:
₹10,000 every month for 15 years.
Advantages include:
- Simple budgeting
- Predictable monthly commitment
- Easy to understand
- Suitable when income is uncertain
Step-Up SIP
The contribution increases periodically.
For example:
₹10,000 per month initially, increasing by 10% each year.
Potential advantages include:
- Higher total contributions
- Better alignment with salary growth
- Greater potential long-term corpus
- Improved ability to address inflation
- Reduced lifestyle inflation
However, Step-Up SIPs also create progressively larger financial commitments.
How Much Should You Increase Your SIP Every Year?
There is no universal percentage suitable for everyone.
A practical increase depends on:
- Annual income growth
- Financial goals
- Monthly expenses
- Existing debt
- Family responsibilities
- Emergency savings
- Investment horizon
Some investors may comfortably increase contributions by 10% annually. Others may prefer 5%, while someone receiving a substantial promotion might increase investments by 15% or more.
A fixed annual increase can also work.
For example, instead of increasing by 10%, you might add ₹2,000 to the monthly SIP every year.
The best step-up is one you can realistically maintain.
When Should You Increase the SIP?
Many investors find it convenient to review SIP amounts once every year.
Good opportunities include:
- After an annual salary increment
- Following a promotion
- After paying off a loan
- When household income increases
- When a major recurring expense ends
- During the annual financial-plan review
You do not necessarily have to wait for a predefined date if your disposable income rises substantially during the year.
Can Step-Up SIP Help You Reach a Goal Earlier?
Potentially, yes.
Suppose two investors have the same expected return and start at the same time. If one continuously increases contributions while the other maintains a fixed SIP, the first investor may reach a given target earlier because more money is being invested.
Alternatively, the investor may maintain the original time horizon and aim for a larger corpus.
Step-up investing can therefore be used to:
- Increase the expected future corpus.
- Reduce a projected funding shortfall.
- Potentially reach a target earlier.
- Adjust savings for inflation.
However, actual mutual-fund returns are market-linked, so future corpus calculations are projections rather than guarantees.
Does a Step-Up SIP Reduce Market Risk?
No.
A Step-Up SIP changes how much you invest, not the underlying risk of the mutual fund.
If your SIP invests in a small-cap fund, increasing the SIP does not make the small-cap portfolio safer.
Similarly, an SIP in a sectoral fund remains concentrated even if investments are made systematically.
Your risk depends primarily on:
- Mutual fund category
- Portfolio composition
- Asset allocation
- Investment horizon
- Market conditions
Step-up investing should therefore be combined with appropriate fund selection and diversification.
Mistakes to Avoid With Step-Up SIPs
Increasing investments is useful only when the strategy remains financially sustainable.
Avoid:
- Choosing an unrealistic annual increase
- Ignoring emergency savings
- Increasing SIPs while carrying expensive debt
- Selecting funds purely from recent returns
- Concentrating all SIPs in small-cap or thematic funds
- Assuming projected returns are guaranteed
- Increasing investments without reviewing asset allocation
- Allowing SIP commitments to create monthly cash-flow stress
A 20% annual step-up may look impressive in a calculator but can become difficult to maintain after several years.
A Practical Step-Up Strategy for Indian Investors
A simple approach is to review your investments after every annual income revision.
Ask:
- How much has my income increased?
- Have my essential expenses changed?
- Are my emergency savings adequate?
- Are my financial goals on track?
- How much of the increment can I invest comfortably?
- Does my existing asset allocation still suit my risk profile?
Then increase SIP contributions accordingly.
The goal is not to maximise the SIP at any cost. It is to gradually increase the amount invested without damaging your present financial stability.
FAQs
Q1. Is a 10% annual Step-Up SIP enough?
A 10% annual increase is commonly used for financial projections, but it is not a mandatory rule. The appropriate increase depends on your salary growth, expenses, goals and financial commitments. Even a smaller sustainable increase can significantly raise total contributions over a long period.
Q2. Can I increase my existing mutual fund SIP instead of starting a new one?
Depending on the mutual fund and platform, you may be able to register a top-up facility or modify your SIP. In some cases, investors may need to create an additional SIP. Check the procedure offered by your fund house or investment platform.
Q3. What happens if I cannot afford the increased SIP later?
You may be able to modify, pause or stop future SIP instructions according to the applicable scheme and platform rules. This normally does not mean your existing mutual-fund units are automatically redeemed. Avoid selecting an aggressive step-up percentage that could create future cash-flow problems.
Q4. Is Step-Up SIP better than investing the same amount every month?
If you can afford increasing contributions, a Step-Up SIP can potentially create a larger long-term corpus because more money is invested over time. However, it does not guarantee better investment returns. Its primary advantage comes from progressively increasing the amount contributed while maintaining investment discipline.